Smurfit Westrock reports fourth-quarter and full-year 2025 results
Smurfit Westrock reported its financial results for the fourth quarter and full year ended December 31, 2025, highlighting resilient performance despite what the company described as difficult market conditions.
For the fourth quarter, net sales totaled $7,580 million. Net income was $98 million, corresponding to a 1.3% net income margin. Adjusted EBITDA reached $1,172 million, with an Adjusted EBITDA margin of 15.5%. Net cash provided by operating activities was $1,195 million, while adjusted free cash flow amounted to $679 million. The company also referenced a previously announced quarterly dividend of $0.4523 per ordinary share, representing a 5% increase.
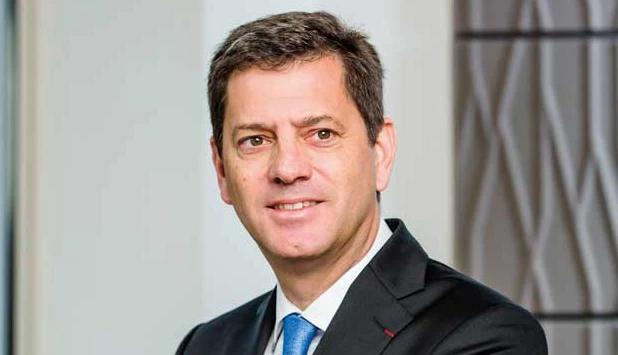
Commenting on the performance, Tony Smurfit, President and CEO, said: “I am pleased to report a strong fourth quarter performance for Smurfit Westrock set against difficult market conditions. We are reporting, for the quarter, Net Income of $98 million and Adjusted EBITDA1 of $1,172 million, with an Adjusted EBITDA Margin1 of 15.5% with a strong Net Cash Provided by Operating Activities of $1,195 million and Adjusted Free Cash Flow1 of $679 million.”
He added that 2025 was focused on building the foundations of the combined company, stating: “In 2025, we established a strong foundation for Smurfit Westrock. We exceeded our committed synergy target of $400 million and put in place a series of customer-centric, commercial and operating initiatives. We also reduced loss making businesses and closed approximately 600,000 tons of high-cost or inefficient capacity as we continued to focus on portfolio optimization.”
Smurfit also said the group continued actions to reshape its operating model during the year, including headcount reductions and investments in assets and efficiency. “During the year, we further reduced headcount by over 3,000, while continuing to invest significantly behind our customers, in our asset base and operating efficiency,” he said, adding that further detail on benefits and future actions would be addressed during the earnings call.
From a regional perspective, the company said North America’s quarterly performance reflected additional downtime taken to balance the system and actively manage working capital. Smurfit noted progress in the shift toward value-based selling, with corrugated operations improving business mix and winning new business. On the consumer side, he cited near-term capacity constraints, “primarily within SBS,” while pointing to continued focus on efficiency, innovation and asset optimization.
For EMEA and APAC, Smurfit highlighted what he described as an “outstanding performance,” supported by an integrated platform and strong market positions, while reiterating confidence in the region’s positioning for recovery. In LATAM, performance was linked to strong market positions and benefits from completed growth projects, with the region described as an area of ongoing opportunity.
Looking ahead, Smurfit said the company expected improved industry operating conditions, despite weather impacts in North America and Europe. “For the first quarter, we currently expect to deliver Adjusted EBITDA3 of between $1.1 billion and $1.2 billion and for the full year, we currently expect to deliver Adjusted EBITDA3 of between $5.0 billion and $5.3 billion,” he said.